The Hidden Value in Underperforming Industrial Assets
By Kyle Gibbons, Head of Acquisitions, CommercialGRP
Some of the most interesting industrial real estate opportunities are not the properties that look perfect on paper.
They may have vacancy. They may need capital improvements. They may have outdated layouts, below-market rents, or operational inefficiencies. At first glance, these characteristics can make an asset appear less attractive than a stabilized property.
But that first impression can be misleading.
In acquisitions, the question I ask is not simply, “How is this property performing today?”
The more important question is:
“What could this property become with the right strategy, capital, and execution?”
That distinction is at the heart of how we evaluate underperforming industrial assets at CommercialGRP.
Our acquisition focus is primarily on industrial properties between 50,000 and 120,000 square feet, along with select retail opportunities. Within that buy box, we look for assets where the fundamentals support a realistic path toward creating long-term value—for investors, tenants, and the surrounding community.
Here are some of the factors we consider.
1. Underperformance Doesn’t Always Mean Poor Fundamentals
An underperforming property and a fundamentally weak property are not necessarily the same thing.
A building may be producing less income than it could because of temporary vacancy, outdated leases, deferred maintenance, inefficient management, or changes in the surrounding market.
Those issues can sometimes be addressed.
Fundamental problems are different.
If the location lacks demand, the building has significant functional limitations, or the economics don’t support a viable business plan, improvements alone may not create enough value to justify the investment.
That is why our first step is separating temporary underperformance from structural weakness.
We look at the property, but we also look at the market surrounding it.
Is industrial demand growing?
Are comparable properties achieving stronger rents?
Does the location provide access to major transportation routes, labor, suppliers, or customers?
Does the building have characteristics that modern industrial users actually need?
The answers help determine whether an asset’s challenges represent opportunity—or simply risk.
2. We Look Beneath the Current Income Statement
Current financial performance tells us what the property is producing today.
It doesn’t necessarily tell us what it could produce tomorrow.
When evaluating an underperforming asset, we examine the components behind the income statement.
That can include:
- Current rents compared with market rents
- Lease expiration schedules
- Occupancy and tenant concentration
- Operating expenses
- Property taxes and insurance
- Maintenance requirements
- Capital expenditure needs
- Historical operating performance
- Comparable properties in the submarket
This analysis helps us identify where performance may be constrained.
For example, a property with below-market rents may have a different opportunity profile than one where rents are already at or above market. Similarly, vacancy may represent potential upside in one location but a warning sign in another.
The numbers have to tell a coherent story.
Our article “What We Look for in Every Industrial Acquisition Opportunity” goes deeper into the fundamentals we examine when determining whether an industrial property deserves further consideration.
The objective isn’t to manufacture an optimistic projection.
It’s to understand the asset realistically.
3. Physical Characteristics Can Reveal Hidden Potential
The building itself is another major part of the equation.
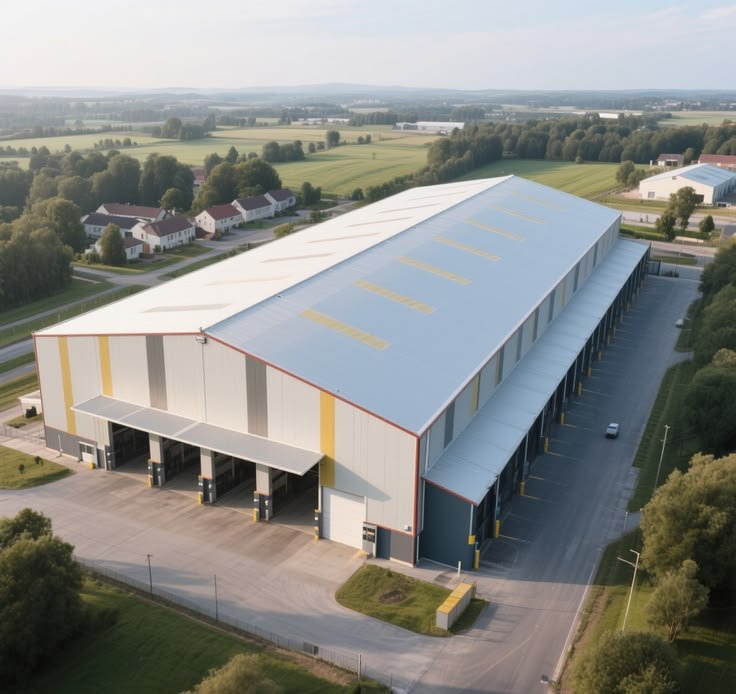
Industrial users increasingly care about functionality. Clear height, loading configuration, parking, truck access, site circulation, power capacity, and building condition can all influence tenant demand.
An underperforming property may have a strong physical foundation even if its current operations don’t reflect that potential.
For example, we may identify opportunities related to:
- Improving loading functionality
- Modernizing common areas
- Addressing deferred maintenance
- Reconfiguring inefficient space
- Improving site circulation
- Upgrading building systems
- Enhancing the property’s overall presentation
But every improvement has a cost.
That is where discipline becomes critical.
We don’t assume that every capital improvement creates value. We evaluate the expected cost, the potential impact on tenant demand or operations, and whether the resulting economics justify the investment.
Value creation has to be supported by the numbers.
4. Tenant and Lease Analysis Can Change the Entire Story
One of the easiest ways to misunderstand an industrial property is to look only at occupancy.
A property that is 100% occupied isn’t automatically a better acquisition than one with vacancy.
The quality and structure of that occupancy matter.
We look at tenant creditworthiness, lease terms, expiration dates, rent levels, renewal probabilities, tenant concentration, and the relationship between current rents and market conditions.
An underperforming property may have strong underlying demand but leases that haven’t kept pace with the market.
Conversely, a property may appear attractive because of high occupancy while carrying significant rollover risk or below-market tenant stability.
This is why we approach underwriting from multiple angles.
The goal is not simply to identify upside.
It is to understand what has to happen for that upside to materialize—and what could prevent it from happening.
That same discipline is reflected in our approach to due diligence. Our article “Property Due Diligence Process: Pre-LOI Checklist for Investors” outlines several of the early questions that can help identify potential opportunities and risks before advancing a transaction.
5. Market Position Matters as Much as the Building
A property cannot be evaluated in isolation.
The surrounding market can determine whether an improvement strategy has a realistic chance of succeeding.
For industrial assets, we examine factors such as:
- Local and regional tenant demand
- Vacancy and absorption
- New construction and supply pipelines
- Rental trends
- Transportation infrastructure
- Labor availability
- Proximity to population centers
- Industrial activity within the submarket
We also consider where the property fits within the broader market.
A building with functional limitations may still be compelling if it occupies a location where industrial land is scarce and tenant demand remains durable.
On the other hand, a property with an attractive purchase price may not be compelling if it sits in a market with weak fundamentals and significant competing supply.
This is why our acquisition process is deliberately analytical.
The property may have hidden value, but the market has to support the strategy.
6. The Best Opportunity Is Often the One With a Clear Path Forward
Finding potential is only the first step.
The next question is whether we can clearly define a path to realizing that potential.
That could involve stabilizing occupancy, improving operations, addressing deferred maintenance, repositioning the property, renewing leases, or making targeted capital improvements.
The key word is targeted.
We are not looking to renovate simply because a building is outdated. We want to understand which improvements matter, why they matter, and whether they support the property’s long-term objectives.
This is where CommercialGRP’s Core Values become particularly important.
Being Motivated & Committed means maintaining discipline throughout the sourcing and evaluation process.
Being Outstanding Communicators means clearly communicating our assumptions, findings, and concerns with investors and transaction partners.
Being Self-Reliant & Detail-Oriented means doing the work required to understand the property rather than relying on surface-level information.
And Honesty and Integrity means acknowledging both the opportunity and the risks.
An acquisition thesis should be strong enough to survive scrutiny.
7. Value Creation Should Extend Beyond the Investment
We evaluate properties with financial discipline, but financial performance isn’t the only consideration.
Commercial real estate affects the communities where it operates.
An underutilized industrial property may represent an opportunity to bring a building back into productive use, support local businesses, accommodate growing companies, or contribute to employment and economic activity.
That is directly connected to CommercialGRP’s Core Focus: transforming communities and improving lives.
For us, that doesn’t mean forcing a community-impact narrative onto every acquisition.
It means asking whether the property can become more productive and useful over time—and whether thoughtful improvements can benefit more than just the ownership group.
The strongest opportunities are those where responsible investment, sound real estate fundamentals, and positive community outcomes can align.
8. The Difference Is in the Evaluation
Underperforming industrial assets can be difficult to evaluate because the current numbers don’t always tell the complete story.
But potential isn’t enough.
At CommercialGRP, we look for opportunities where the fundamentals, market, physical asset, tenant situation, pricing, and value-creation strategy work together.
Sometimes that leads us to pursue an acquisition.
Sometimes it leads us to walk away.
Both outcomes are part of a disciplined acquisition strategy.
Our responsibility is not to find a reason to buy every property we review. It is to identify the opportunities where the risk is understandable, the strategy is realistic, and the potential value is supported by thorough analysis.
That approach is also reflected in “How We Underwrite Industrial Deals: A Step-by-Step Breakdown,” which explores how disciplined underwriting helps separate assumptions from what the underlying property can realistically support.
Let’s Connect
If you’re an investor interested in understanding how we evaluate industrial and select retail opportunities, I’d welcome the conversation.
Our focus is on properties that fit our acquisition criteria, but we’re equally focused on the quality of the underlying opportunity and the path toward long-term value creation.
If you’d like to learn more about our acquisition strategy or discuss an opportunity that may fit our buy box, let’s connect.
The most interesting properties aren’t always the ones that look perfect today.
Sometimes, they’re the ones where the fundamentals give us a reason to believe they can become something better tomorrow.
This article is provided for informational purposes only and does not constitute legal, tax, financial, or investment advice. Any investment involves risk, and readers should consult their own qualified professional advisors regarding their individual circumstances.